
10 Best HVAC Financing Companies (2026): Who to Hire and What It Costs
Compare the 10 best hvac financing companies on APR, loan limits and dealer fees for homeowners and HVAC contractors, with every rate checked November 8, 2026.
 Shamim Mia, Founder, SerpAstraLast verified November 8, 202614 min read
We compare pricing pages, documentation and public reviews. We never accept payment for rankings.
Key takeaways
- Wisetack leads for most HVAC shops at a flat 3.9% per financed job; Synchrony follows with branded 0% APR cards, and Hearth suits big tickets at $1,499 a year with loans to $250,000.
- The single most important buying factor is who pays for the 0% promotion: the dealer fee runs 4% to 13% of the job, and most 0% plans are deferred interest, not true 0%.
- Loan limits decide the shortlist: Hearth reaches $250,000, GreenSky and Service Finance reach $100,000, Wisetack stops at $65,000 and SoFi starts at a $5,000 minimum.
- LightStream is not in this list: it stopped accepting new loan applications on October 17, 2026.
On this page
Quick comparison
| Tool | Best for | Starting price | Free plan |
|---|---|---|---|
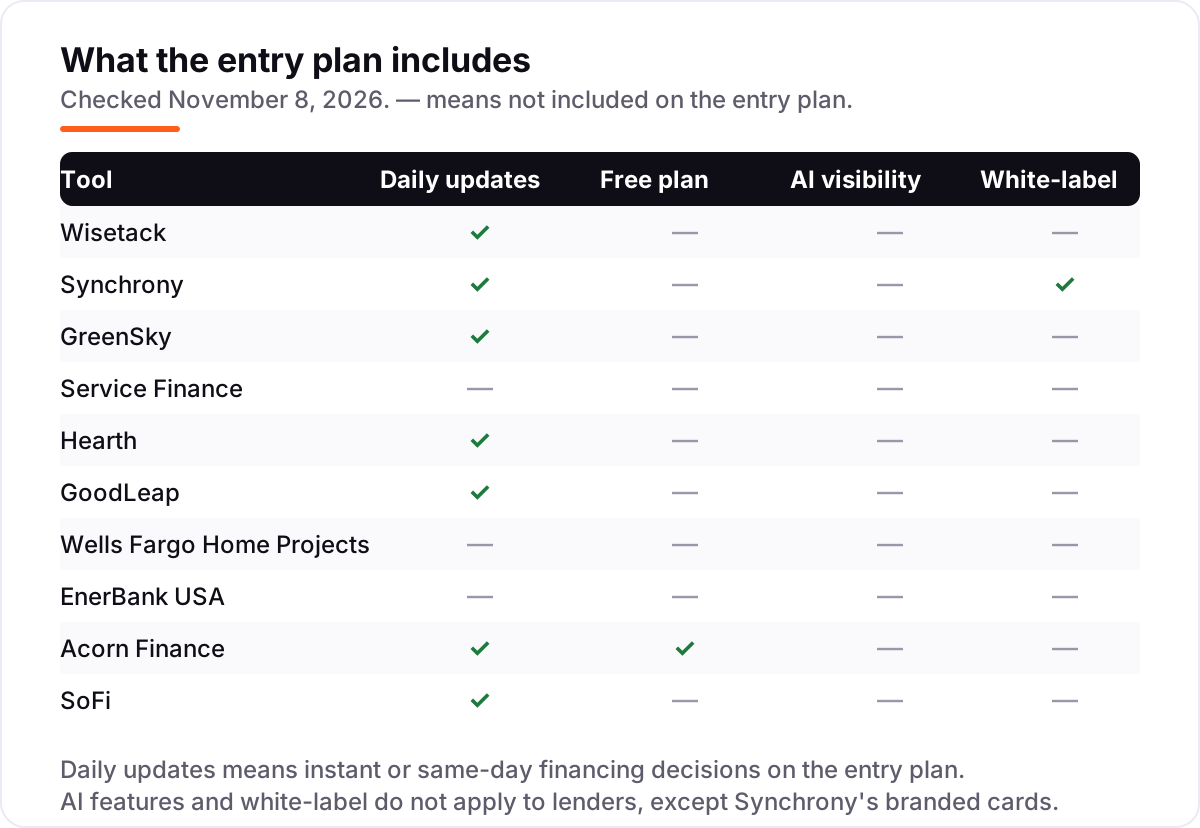
| Wisetack | HVAC shops of any size that want financing inside Jobber, Housecall Pro or ServiceTitan with no subscription | 3.9% per job | No (lender) |
| Synchrony | Manufacturer dealers who want the branded HVAC card customers already recognize, with 0% promos | Custom quote | No (lender) |
| GreenSky | Multi-truck HVAC shops doing $5 million or more a year that need 0% firepower on $15,000 replacements | Custom quote | No (lender) |
| Service Finance | Lennox, Carrier, Trane and Bryant dealers who want manufacturer-subsidized promos and $100,000 limits | Custom quote | No (lender) |
| Hearth | Contractors financing big tickets above $65,000 and homeowners with FICO scores from 550 | From $1,499/yr | No (lender) |
| GoodLeap | Homeowners planning heat pump conversions and electrification jobs that need a low fixed payment over 10 to 15 years | Custom quote | No (lender) |
| Wells Fargo Home Projects | Any-brand HVAC dealers who want a bank-backed card with a 0% 12-month plan or a 9.99% 96-month plan | Custom quote | No (lender) |
| EnerBank USA | Dealers who already offer EnerBank and want a specialist home-improvement lender with 0% same-as-cash loans | Custom quote | No (lender) |
| Acorn Finance | Contractors who want to offer financing with no dealer fee and no subscription, through a 30-lender marketplace | No contractor fee | Yes (free) |
| SoFi | Homeowners with good to excellent credit who would rather borrow directly than use a contractor's financing | No origination fee | No (lender) |
Make one of these tools?
We re-check this list every quarter. Send a correction, request a review, or ask about a clearly labeled sponsored spot.
Request a listingThe best hvac financing companies
Wisetack
Best for: HVAC shops of any size that want financing inside Jobber, Housecall Pro or ServiceTitan with no subscription
Wisetack is the easiest financing to add: there is no subscription and no enrollment fee, just a flat 3.9% fee on each financed job. Homeowners prequalify with a soft credit check that does not affect their score, then choose from up to eight offers at 0% to 35.9% APR over 3 to 120 months. Loans run from $500 to $65,000, which covers most repairs and full system replacements.
The contractor is paid by bank transfer one to three business days after the job is completed, and the platform plugs into Jobber, Housecall Pro, ServiceTitan and 30-plus other field-service tools. The catch is the 0% promotions: they are optional add-ons that raise the merchant fee, up to 9.9% for a 24-month 0% plan. Choose Wisetack when you want financing inside the software you already use.
What we like
- Flat 3.9% fee per financed job with no subscription, setup fee or monthly minimum
- Native integrations in Jobber, Housecall Pro, ServiceTitan and 30+ field-service tools
- Soft-pull prequalification in about 60 seconds, with up to eight offers per homeowner
- Contractor paid by bank transfer 1 to 3 business days after the job is completed
Watch out for
- Loans top out at $65,000, so whole-home jobs above that need a second lender
- 0% promotions cost extra — up to 9.9% merchant fee for a 24-month 0% plan
- Homeowner APRs run to 35.9% for lower-credit borrowers
Synchrony
Best for: Manufacturer dealers who want the branded HVAC card customers already recognize, with 0% promos
Synchrony is the bank behind most branded HVAC cards, including the Carrier Comfort Card and the Trane card. Homeowners get a reusable revolving credit line, with promotional 0% APR plans for 12 to 60 months and fixed-rate terms to 120 months. Approval takes about five minutes with a soft credit pull; the card works only at participating dealers.
The dealer fee is the real cost: standard-rate plans cost the contractor little or nothing, while long 0% promotions run 7% to 12% or more of the ticket. The other trap is deferred interest — if the balance is not paid in full by the end of the promo, interest is charged from the purchase date at the standard APR. Pick Synchrony when you are a manufacturer dealer and want the card your customers already recognize.
What we like
- Branded cards for Carrier, Trane, Lennox and other manufacturers that customers already trust
- Promotional 0% APR plans for 12 to 60 months, with fixed-rate terms to 120 months
- Revolving credit line the homeowner can reuse for later repairs
- Approval in about five minutes with a soft credit pull
Watch out for
- Most 0% offers are deferred interest — unpaid balances are charged interest from the purchase date
- Long 0% promotions cost the dealer 7% to 12% or more of the ticket
- Standard APR runs about 26.99% to 29.99% once a promotion ends
GreenSky
Best for: Multi-truck HVAC shops doing $5 million or more a year that need 0% firepower on $15,000 replacements
GreenSky is the oldest large home-improvement lender in this list, with more than $30 billion in originations, and it is built for big tickets: loans run to $100,000 with terms to 12 years. Reduced-rate plans run roughly 5.99% to 11.99% APR, and deferred-interest promotions offer no interest if the balance is paid in full within the promotional window. Homeowners apply in about 90 seconds through the contractor.
The dealer fee is the trade-off. Standard 9.99% APR plans cost the contractor nothing, but 0% promotional plans run 4.99% to 12.99% of the job, and underwriting has tightened since the Goldman Sachs era — approval rates fell for borrowers in the 660 to 700 FICO range. GreenSky suits multi-truck HVAC shops doing $5 million or more a year that need 0% firepower to close $15,000 replacements.
What we like
- Loans to $100,000 with terms to 12 years, the largest limits beside Service Finance
- Reduced-rate plans from 5.99% to 11.99% APR for qualified borrowers
- Application takes about 90 seconds through the contractor
- The largest home-improvement financing platform in the US, with over $30 billion originated
Watch out for
- Deferred-interest promos charge interest from day one if the balance is not paid in full
- 0% promotional plans cost the dealer 4.99% to 12.99% of the job
- Underwriting tightened after the Goldman Sachs era, with lower approvals at 660 to 700 FICO

Service Finance
Best for: Lennox, Carrier, Trane and Bryant dealers who want manufacturer-subsidized promos and $100,000 limits
Service Finance Company, owned by Truist Bank, is the lender most deeply embedded in HVAC manufacturer dealer programs: Lennox Premier Dealers, Carrier President's Award dealers, Trane Comfort Specialists and Bryant Factory Authorized Dealers usually have it pre-loaded. Loans run to $100,000 per project, the highest limit in this list, with 0% APR promotions and standard plans at 9.99% APR.
Standard-rate plans typically cost the dealer nothing, while 0% promotions for 12 to 24 months run 6.5% to 9.9% in dealer fees, and 60-month 0% promotions run 4% to 7%. Funding takes 24 to 72 hours after completion, slower than Wisetack, and customer service draws the most complaints in this category. Choose Service Finance when you sell through a manufacturer dealer program and want its subsidized seasonal promotions.
What we like
- Pre-loaded in Lennox, Carrier, Trane and Bryant manufacturer dealer programs
- Loans to $100,000 per project, the highest limit in this list
- Standard 9.99% APR plans typically cost the dealer nothing
- Manufacturer-subsidized seasonal promotions on 0% plans
Watch out for
- 0% promotions for 12 to 24 months run 6.5% to 9.9% in dealer fees
- Funding takes 24 to 72 hours after completion, slower than Wisetack
- Customer service draws the most complaints in this category, per 2026 contractor comparisons
Hearth
Best for: Contractors financing big tickets above $65,000 and homeowners with FICO scores from 550
Hearth is a marketplace, not a lender: one prequalification form reaches 18 lending partners, with loans from $1,000 to $250,000, terms from 2 to 12 years, and rates from 4.99% APR for borrowers with FICO scores as low as 550. There is no per-loan dealer fee — the contractor pays a flat annual subscription instead — and 0% introductory APR card options are available for qualifying homeowners.
The subscription is the decision. Hearth's own 2026 comparison puts most companies at $1,499 to $4,999 a year, which pays off once you finance regularly but stings if you only finance a few jobs a year. Hearth also bundles estimates, e-signed contracts, invoicing and an AI receptionist, so it is really a sales platform with financing inside. Pick Hearth for big tickets above Wisetack's $65,000 ceiling and for lower-credit homeowners.
What we like
- One form reaches 18 lenders, with loans from $1,000 to $250,000
- No per-loan dealer fee — a flat annual subscription keeps 100% of each job's revenue
- Serves FICO scores from 550, with rates from 4.99% APR
- Bundles estimates, e-signed contracts, invoicing and an AI receptionist
Watch out for
- Subscription runs $1,499 to $4,999 a year, which stings if you finance only a few jobs
- Hearth is a broker, not a lender — the rate and terms come from third-party lenders
- Auto-renewal and cancellation complaints show up in reviews; calendar the renewal date
GoodLeap
Best for: Homeowners planning heat pump conversions and electrification jobs that need a low fixed payment over 10 to 15 years
GoodLeap started in solar and has pushed hard into HVAC over the last two years, and its strength is long, low-APR installment loans rather than short 0% promotions. Home-improvement loans run to $55,000 with fixed rates, no upfront costs and terms of 5 to 15 years, and there is no prepayment penalty. An 18-month no-interest, no-payments promotion is available on qualifying projects.
The dealer fee on long-term low-APR products runs 6% to 12% of the ticket, which is the price of the low rate — the contractor subsidizes it. GoodLeap returns up to three loan options with estimated monthly payments, and AutoPay earns a 0.50% rate discount. Choose GoodLeap for whole-home heat pump conversions and electrification jobs where a low fixed payment over 10 to 15 years beats a short promo.
What we like
- Fixed low-APR installment loans with terms to 15 years, not just short promos
- Loans to $55,000 with no upfront costs and no prepayment penalty
- 18-month no-interest, no-payments promotion on qualifying projects
- AutoPay earns a 0.50% rate discount
Watch out for
- Long-term low-APR products cost the dealer 6% to 12% of the ticket
- Wrong tool for a short 0% close on a $9,000 furnace swap
- No single published APR — the rate is set at the credit review for each borrower
Wells Fargo Home Projects
Best for: Any-brand HVAC dealers who want a bank-backed card with a 0% 12-month plan or a 9.99% 96-month plan
Wells Fargo Home Projects is the credit card behind many HVAC dealers' financing, and it works with any brand of equipment. Two plans cover most jobs: 0% APR for 12 months if the balance is paid in full, or 9.99% APR with 96 equal monthly payments. The minimum purchase is $1,000, and the card carries no annual fee.
The number to respect is the standard APR: 28.99% for new accounts, charged from the purchase date if a 0% balance is not paid in full within the promotional period. That makes the 12-month plan a same-as-cash deal only for homeowners who can actually clear the balance in a year. Pick Wells Fargo when you want a bank-backed card that any brand dealer can offer, and steer disciplined buyers to the 9.99% plan when the balance will last longer.
What we like
- Works with any HVAC brand, not just one manufacturer's dealers
- 0% APR for 12 months if paid in full, or 9.99% APR over 96 equal payments
- No annual fee on the Home Projects card
- Bank-backed program with a long track record in home improvement
Watch out for
- Standard APR is 28.99% for new accounts if a 0% balance is not paid in full
- The 0% plan is deferred interest in practice — interest is charged from the purchase date
- Minimum purchase of $1,000 rules out small repairs

EnerBank USA
Best for: Dealers who already offer EnerBank and want a specialist home-improvement lender with 0% same-as-cash loans
EnerBank USA, a Regions Bank brand and FDIC-insured lender, has specialized in home-improvement loans since 2001. Loans run from $1,000 to $100,000, with 0% same-as-cash loans for 12 months and reduced-rate installment loans from 6.99% APR. Terms run to 12 years on some plans, and dealer materials report about four in five applicants are approved.
EnerBank publishes no single public rate card — the plans and dealer fees are set per dealer, so the option sheet your dealer hands you is the only firm quote. Dealer fees run about 6% on 12 to 18-month 0% loans, and the 12-month same-as-cash loan accrues interest at about 17.99% if it is not repaid within the year. Choose EnerBank when your dealer already offers it and you want a specialist lender with a long HVAC track record.
What we like
- Specialist home-improvement lender since 2001, FDIC-insured through Regions Bank
- 0% same-as-cash loans for 12 months alongside reduced-rate loans from 6.99% APR
- Loans from $1,000 to $100,000 with terms to 12 years
- Dealer materials report about four in five applicants are approved
Watch out for
- No single public rate card — plans and dealer fees are set per dealer
- The 12-month same-as-cash loan accrues interest at about 17.99% if not repaid in time
- Dealer fees run about 6% on 12 to 18-month 0% loans
Acorn Finance
Best for: Contractors who want to offer financing with no dealer fee and no subscription, through a 30-lender marketplace
Acorn Finance is a free marketplace that compares loan offers from 30 or more competing lenders in about 60 seconds, with no hard credit check to see the offers. Home-improvement loans run from $1,000 to $100,000 with APRs from 6.99% to 35.99% and terms from 12 to 144 months, for borrowers with credit scores from 550. Contractors pay no dealer fees at all.
Because Acorn is a marketplace, the rate and lender change with the borrower's credit — the headline 6.99% APR needs excellent credit, and the featured Upgrade loans carry a 1.85% to 9.99% origination fee deducted from the proceeds. Acorn added 0% APR promotional financing in April 2025, and most loans fund within 48 hours of approval. Pick Acorn when you want to offer financing without paying a dealer fee or a subscription.
What we like
- Free to compare: 30+ lenders in about 60 seconds with no hard credit check
- No dealer fee and no subscription for contractors
- Loans from $1,000 to $100,000 with terms to 144 months, FICO from 550
- 0% APR promotional financing added in April 2025
Watch out for
- Headline 6.99% APR needs excellent credit; most borrowers see higher rates
- Featured Upgrade loans carry a 1.85% to 9.99% origination fee taken from the proceeds
- Acorn is a marketplace, not a lender — the loan terms come from third-party lenders
SoFi
Best for: Homeowners with good to excellent credit who would rather borrow directly than use a contractor's financing
SoFi is the direct personal-loan option in this list: homeowners borrow $5,000 to $100,000 themselves, with fixed APRs from 6.99% to 35.49% with all discounts and terms from two to seven years. There is no required origination fee, no prepayment penalty and no late fee, and funding can land the same day the loan is approved. The rate check uses a soft credit pull.
The catch is the floor: the $5,000 minimum rules out small repairs, and the lowest rates need good to excellent credit — SoFi's average approved borrower carries about a 746 FICO — plus autopay and a member discount that requires direct deposit or qualifying deposits. SoFi works best as the borrow-it-yourself backup when the contractor's own financing declines the homeowner or the job is too small for a dealer program.
What we like
- No required origination fee, no prepayment penalty and no late fee
- Loans from $5,000 to $100,000 with same-day funding on approval
- Fixed APRs from 6.99% to 35.49% with all discounts, terms of two to seven years
- Rate check uses a soft credit pull that does not affect the borrower's score
Watch out for
- $5,000 minimum rules out small repairs and single-component replacements
- Lowest rates need good to excellent credit plus autopay and a member discount
- Not a contractor program — the homeowner applies alone, with no dealer support
The 10 best hvac financing companies below fall into two groups: contractor programs that put financing on the quote, and direct loans the homeowner arranges alone. We ranked them by fit for the most common buyer — an HVAC contractor who wants more replacements closed, and the homeowner paying for one — starting with the cheapest dealer cost and ending with the borrow-it-yourself options, and every APR, loan limit and dealer fee was checked on November 8, 2026.
How to choose the best hvac financing companies
- Count the dealer fee first. The fee is the contractor's real cost: 3.9% per job on Wisetack, 5% to 13% on most 0% promotions, or a flat $1,499 to $4,999 a year on Hearth. A program that looks free to the homeowner is never free to the shop.
- Ask whether the 0% plan is deferred interest. Most 0% HVAC offers accrue interest from the purchase date and charge it all if the balance is not paid in full. True 0% APR plans exist, but they are the exception, not the rule.
- Match the loan limit to the ticket. Wisetack stops at $65,000, GreenSky and Service Finance reach $100,000, and Hearth reaches $250,000. A program whose ceiling sits below your average replacement cannot close your average replacement.
- Check the credit floor. Hearth and Acorn Finance serve FICO scores from 550, while Synchrony's 0% promotions and SoFi's lowest rates need good to excellent credit. The floor decides how many of your customers actually qualify.
- Check funding speed. Wisetack pays in one to three business days after completion, Hearth in 24 to 48 hours, and Service Finance in 24 to 72 hours. Slow funding is a cash-flow cost, not just an inconvenience.
- Decide who applies. Contractor programs put the application on the quote at the kitchen table; personal loans like SoFi leave the homeowner to apply alone. The first closes more jobs.
Financing closes more jobs, but only if homeowners find the business first — our local SEO service covers the visibility side. And once a financed job is done, ask for the review while the customer is still happy: the free Google review link generator builds a one-tap review link for the business.
Whatever you shortlist, run one real job through it before you commit the whole season to it. Offer the financing on a live quote, watch how the homeowner reacts to the monthly payment, and check that the funding lands when the lender says it will. The programs in this list all prequalify with a soft credit check, so the trial costs the homeowner nothing and tells you more than any brochure can.
HVAC financing companies pricing: what you will actually pay
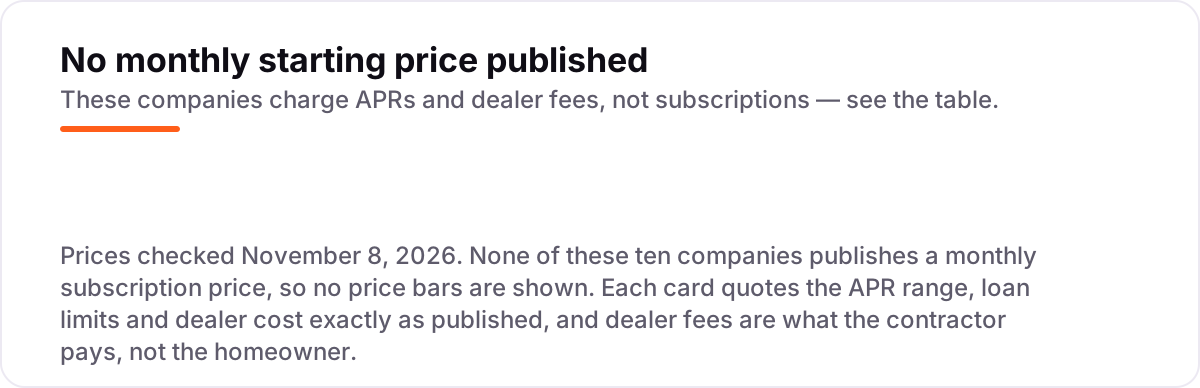
Take a $12,000 full system replacement. On Wisetack's standard plan the contractor pays 3.9% of the job, or $468, and the homeowner's payment follows the APR: Wisetack's own published example is $253.54 a month for a $5,500 loan at 9.9% APR over 24 months, which scales to about $553 a month on $12,000 at the same rate and term. On a 0% promotion for 18 months the homeowner pays $667 a month and nothing in interest — but the dealer fee at 9% is $1,080, more than double the standard-plan fee.
Now run the same $12,000 job through the subscription model. Hearth charges $1,499 a year with no per-loan fee, so a shop that finances 20 jobs a year at $12,000 each pays $1,499 on Hearth against $9,360 on Wisetack's standard plan — a $7,861 gap that only exists because the volume is high. At three financed jobs a year the math flips: $1,404 on Wisetack against $1,499 on Hearth, and the subscription loses. Hearth breaks even against Wisetack's 3.9% fee at about $38,400 of financed volume a year.
Two more numbers to carry into the decision. First, the long-term option: GoodLeap's published example puts a $10,000 loan at 7% APR at about $116 a month over 10 years, which is how a heat pump conversion becomes a utility-bill-sized payment — but the dealer pays 6% to 12% of the ticket for that low rate. Second, the penalty for missing a promo deadline: a $12,000 balance left unpaid after a 12-month 0% plan starts accruing interest at the standard APR, about 26.99% to 29.99% on Synchrony and Wells Fargo, charged from the purchase date. If you run a contracting business rather than a one-off project, the payment side matters too — see our guide to the best contractor payment software.
Know the difference: deferred interest vs true 0% APR
The confusion in this category is between two products that are both sold as "0% financing." With true 0% APR, no interest accrues during the promotional period: the homeowner owes exactly what was borrowed, and paying it off on time costs nothing extra. With deferred interest, interest accrues at the full standard APR — typically 26.99% to 29.99% on Synchrony and Wells Fargo plans — from the purchase date, and it is only waived if the full balance is paid before the promotion ends. If even one dollar remains, the entire accrued interest becomes due at once.
The second confusion is who pays for the promotion. A 0% offer is never free money: the lender recovers the interest from the contractor through the dealer fee, which runs 5% to 13% of the job on most 0% plans. That fee is why a shop that pushes 0% on every quote can close more jobs and still earn less per job. Wisetack is the most transparent about this — its 24-month 0% plan costs up to 9.9% against 3.9% for a standard-rate plan — while GreenSky, Synchrony and Service Finance set the fee per plan and per dealer.
A third distinction worth knowing is dealer financing versus a personal loan. Dealer financing is arranged at the quote, through the contractor's program, and the lender pays the contractor directly. A personal loan from SoFi or a marketplace is borrowed by the homeowner alone and paid to the contractor as cash. The personal loan is the fallback when the dealer program declines the homeowner, when the job is too small for a dealer minimum, or when the homeowner simply prefers to keep the contractor out of their credit.
Quick comparison: tool type by need
| Buyer | Best pick | Why |
|---|---|---|
| Small HVAC shop, first financing offer | Wisetack | No subscription, 3.9% per job, inside the software you already use |
| Manufacturer dealer (Carrier, Trane, Lennox) | Synchrony or Service Finance | Branded cards and subsidized promos, limits to $100,000 |
| Big-ticket jobs over $65,000 | Hearth | Loans to $250,000, flat subscription, FICO from 550 |
| Heat pump conversion, long low payment | GoodLeap | Fixed low APR over 5 to 15 years, loans to $55,000 |
| Homeowner borrowing alone | SoFi | $5,000 to $100,000, no required origination fee, same-day funding |
| No dealer fee at all | Acorn Finance | Free 30-lender marketplace, homeowner APRs from 6.99% |
Mistakes to avoid
- Selling a 0% plan without checking deferred interest. If the plan accrues interest from day one, a customer who misses the deadline by a month owes 12 months of interest at 26% to 29%. Confirm in writing whether the plan is deferred interest or true 0%.
- Budgeting on the headline APR. The lowest APRs need excellent credit: 6.99% at SoFi and Acorn, 4.99% at Hearth. Most borrowers see a higher rate, so compare offers on the APR the customer actually qualifies for.
- Picking a lender whose limit is below your average ticket. Wisetack's $65,000 ceiling covers most replacements, but a whole-home job with ductwork and electrical work can pass it. Check the ceiling before you print it on the quote.
- Ignoring the dealer fee in the job price. A 9% fee on a $12,000 job is $1,080 out of the margin. Price financed jobs with the fee in the number, or the close-rate lift from financing can still lose money.
- Offering financing with no second-look path. A prime lender declines a large share of applicants. Keep a marketplace like Hearth or Acorn behind the first offer so a decline becomes a second offer, not a lost job.
How we chose
We checked each lender's own published terms on November 8, 2026 and recorded the APR range, loan limits and dealer cost exactly as published, and we ranked the companies by fit for the most common buyer — an HVAC contractor who wants more replacements closed — not by brand size. Where a lender publishes no public rate card, we used the terms shown on dealer and manufacturer program pages and on independent 2026 comparisons that quote the vendor's own materials: that applies to Synchrony, GreenSky, Service Finance, Wells Fargo and EnerBank, whose plans and dealer fees are set per dealer. This list carries only two review ratings — Wisetack at 4.6 out of 5 on G2 (26 reviews) and Hearth at 4.7 out of 5 on Trustpilot (1,734 reviews) — because the other lenders' review pages are fragmented across several profiles or could not be verified, and we would rather show no rating than a stale or estimated one. LightStream was left out because it stopped accepting new loan applications on October 17, 2026, and Upgrade was left out for space: it overlaps Acorn Finance and SoFi as a fair-credit personal loan. No vendor paid for a place in this list, and none of the links here are affiliate links.
What to do next
Start with the program that matches your average ticket: Wisetack if most jobs sit under $65,000, Hearth if they run above it, and a marketplace behind either one for the customers the first lender declines. Put the financing offer on the quote itself, not on a flyer in the truck, and train the tech to state the monthly payment before the total. If the jobs are coming in but the phones are not ringing, compare providers in our guide to marketing software for contractors. Once your tools are in place, find out what's holding your rankings back.
Your stack only works if people find you
SerpAstra fixes what keeps your site off page one and makes it easy for AI assistants to recommend.
Get a free audit→Sources we checked (17)
- Wisetack vs GreenSky — wisetack.com/compare/wisetack-vs-greensky (checked November 8, 2026)
- Synchrony HVAC financing terms — halescornersheating.com/hvac-financing (checked November 8, 2026)
- Synchrony HVAC financing plans — icareaircare.com/financing (checked November 8, 2026)
- Contractor financing programs compared — power100.io (checked November 8, 2026)
- GreenSky personal loans review — credible.com (checked November 8, 2026)
- HVAC financing solutions for homeowners — pipelineon.com/blog/hvac-financing (checked November 8, 2026)
- Hearth vs Service Finance vs GreenSky vs Wisetack — alelitefinancing.com (checked November 8, 2026)
- Hearth customer financing for contractors — gethearth.com/customer-financing-for-contractors (checked November 8, 2026)
- Hearth vs Enhancify — gethearth.com/hearth-vs-enhancify (checked November 8, 2026)
- GoodLeap HVAC financing rates — retrotreat.com (checked November 8, 2026)
- GoodLeap HVAC financing — thecoolingco.com/hvac-financing (checked November 8, 2026)
- Wells Fargo HVAC financing — unicolor.com/financing/wells-fargo-financing-carrier (checked November 8, 2026)
- EnerBank USA financing — learn.trades.org (checked November 8, 2026)
- Acorn Finance contractor financing — acornfinance.com (checked November 8, 2026)
- SoFi personal loans review — money.com (checked November 8, 2026)
- Wisetack reviews — g2.com/products/wisetack/reviews (checked November 8, 2026)
- Hearth reviews — uk.trustpilot.com/review/gethearth.com (checked November 8, 2026)
Shamim
Founder of SerpAstra
A full-stack SEO and digital marketer who spends most days on Local SEO for dental practices, AI search visibility and lead generation.
Frequently asked questions
What is the best HVAC financing company?
Wisetack is the best fit for most HVAC shops: a flat 3.9% fee per financed job, no subscription, and financing inside Jobber, Housecall Pro and ServiceTitan. Synchrony is the better pick for manufacturer dealers who want a branded card with 0% promotions, and Hearth suits big tickets above $65,000. Homeowners borrowing alone should start with SoFi.
How much does HVAC financing cost?
It depends on who pays. The contractor pays a dealer fee of 3.9% per job on Wisetack, 5% to 13% on most 0% promotions, or a flat $1,499 to $4,999 a year on Hearth. The homeowner pays the APR, from 0% on a promotion paid in full to 35.9% for lower-credit borrowers. Always compare the dealer fee and the APR together.
What credit score do you need for HVAC financing?
It varies by lender. Hearth and Acorn Finance serve borrowers with FICO scores from 550. Synchrony's 0% promotions typically need fair to good credit, around 640 or higher, and SoFi's lowest rates need good to excellent credit. A decline from one lender is not a decline from all of them, so a marketplace like Hearth or Acorn is the fallback.
Is 0% HVAC financing really free?
Only if it is true 0% APR and you pay the balance in full before the promotion ends. Most 0% HVAC offers are deferred interest: interest accrues at the standard APR, often 26% to 29%, from the purchase date, and the whole amount becomes due if even one dollar remains. Ask the dealer to confirm in writing whether the plan is deferred interest or true 0%.
Can I finance an HVAC system with bad credit?
Yes, with limits. Hearth and Acorn Finance accept FICO scores from 550 through their lending partners, and their rates start at 4.99% and 6.99% APR for the best-qualified borrowers. Expect a higher APR and a shorter term than a prime borrower gets, and compare the total cost, not just the monthly payment. A marketplace gives you several offers to compare at once.
Should I use dealer financing or a personal loan?
Dealer financing is faster and usually cheaper at the point of sale: the contractor handles the application, and 0% promotions beat any personal loan. A personal loan from SoFi or a marketplace suits homeowners who want to borrow independently, need more than the dealer program covers, or were declined by the contractor's lender. Compare the APR and the total interest, not the monthly payment alone.
How fast do HVAC financing companies pay the contractor?
Wisetack pays by bank transfer one to three business days after the job is completed, and Hearth funds in 24 to 48 hours. Service Finance takes 24 to 72 hours after completion. The homeowner's approval is usually instant, with a soft credit check that does not affect their score, so the funding clock starts at completion, not at application.
Free SEO and AI visibility audit
Find out what is holding your rankings back
Send us your site. Within 2 business days you get a written audit, an AI visibility check and a short fix list ranked by impact. Free, with no contract attached.
Request my free audit→Related guides
 Local Business & Vertical Software7 Best Contractor Payment Software in 2026, ComparedCompare the 7 best contractor payment software options on price, countries covered and compliance, with every price checked November 7, 2026.Read guide →
 Digital Marketing & Ads7 Best Marketing Software for Contractors in 2026, ComparedCompare the 7 best marketing software for contractors on price, reviews and trade-specific features, with every price checked November 5, 2026.Read guide →
 Local Business & Vertical Software8 Best Estimating Software for Contractors in 2026, ComparedCompare the 8 best estimating software for contractors on price, takeoff, cost databases and free trials, with every price checked November 7, 2026.Read guide →